Habits

Habits

Turn every expense you cut into automatic savings

October 15, 2026

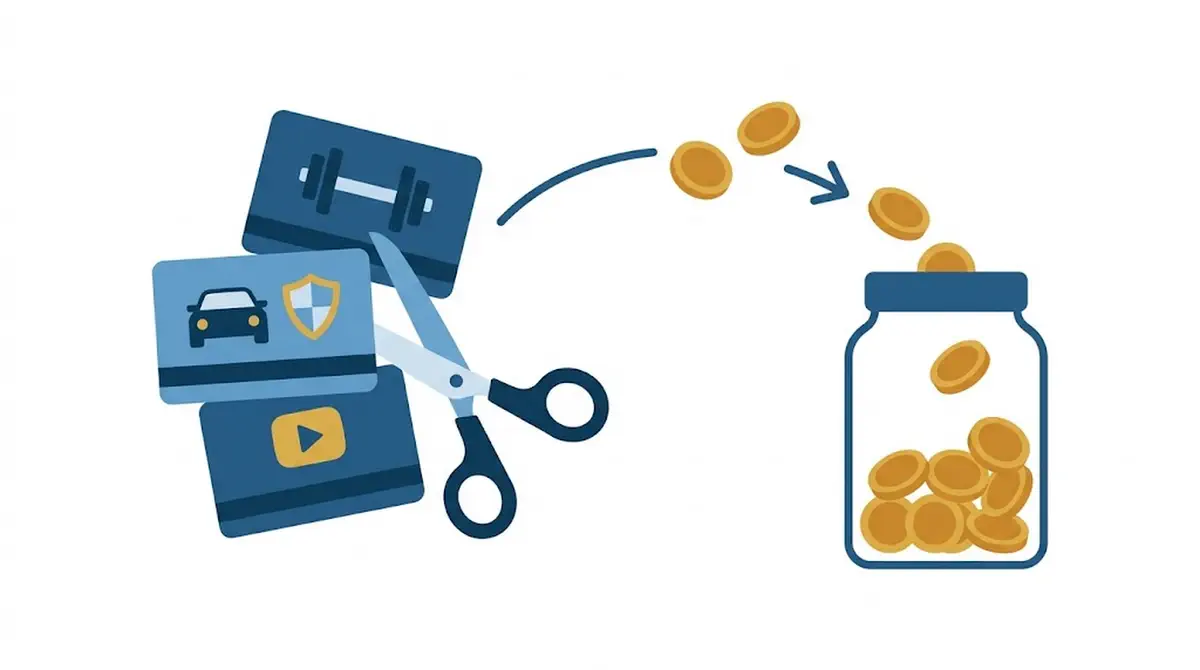
You cancelled the gym membership you hadn’t used in months. You renegotiated your car insurance and got the premium lowered. You unsubscribed from a streaming service you didn’t even remember you had. That money, in theory, is extra savings every month. In practice, it almost never is: it mixes in with the rest of your available balance, and two months later you couldn’t say where it went.

The tip: move it the same day you cut it

The moment you cancel or renegotiate an expense is the best moment to decide where that money goes, for two reasons. You have the exact figure freshly calculated in front of you, and you haven’t yet gotten used to having that money available every month. If you wait, both advantages disappear: the figure gets blurry and the new margin starts to feel like “just how things are,” the exact same mechanism by which a pay rise dissolves on its own if you don’t give it a destination.
personal finance savings recurring expenses habits
Habits

The 'don't touch' account: add deliberate friction to your savings

October 6, 2026

You have a savings fund, you know you’re not supposed to touch it, and you touch it anyway. Not because you lack discipline: because it’s two taps away, in the same app where you check your everyday account balance. Any Friday-night craving finds that money with zero effort.

The tip: make withdrawing it cost something

The fix isn’t more willpower, it’s less convenience. Put deliberate friction between you and that money, so there’s a real obstacle between the impulse and the transfer, not just a good intention. Three levels, from least to most friction:

personal finance savings habits emergency fund
Habits

Raise your savings every time you get a raise

September 17, 2026

You get a raise, and a few months later you’re living exactly as tight as before it. Nothing strange happened: you changed cars, eat out a bit more, the flat is “nicer” now. Each new expense made sense on its own. The problem is that, added up, they swallowed the whole raise, and your savings are still the same number as before.

The tip: raise your savings, not your spending

It’s called lifestyle inflation: the more you earn, the more you spend, in the same proportion, without ever deciding it consciously. It’s not a character flaw — it’s what happens by default if you don’t do anything: the new money lands in the same account as always and quietly splits itself among things you were already itching to upgrade.

personal finance savings salary habits
Habits

Automate it so it doesn't depend on willpower

September 3, 2026

You decide to save more, stop impulse buying, or never pay a bill late again. It works for two weeks. Then a rough month shows up, you let your guard down for one day, and the resolution quietly fades without you ever deciding to give up. It’s not that you lack willpower: you’re using it on the wrong job.

The tip: let the system decide, not you every time

Willpower is a resource that runs out. Every decision you have to make again — do I set money aside this month? do I pay this bill now or later? do I buy this or not? — is a chance for the easy path to win. An automatic system never gives you that chance: the decision is already made once, and it runs on its own whether you remember or not, whether you’re having a good day or a terrible one.

personal finance automation savings habits
Habits

Pay yourself first: automate your savings on payday

August 27, 2026

You get paid, cover the usual bills, and at the end of the month you look at whatever’s left to “save.” Most months there isn’t much, and some months there’s nothing. The problem isn’t that you earn too little or spend badly: it’s the order. If savings go last in line, they lose to whatever expense shows up first.

The tip: flip the order

The idea fits in one sentence: treat savings like just another fixed bill, not like whatever’s left over. Instead of spending and seeing what remains, set aside a fixed amount first — an automatic transfer, the same day or the day after you get paid — and live on what’s left afterward. Money that never reaches your everyday checking account is money you won’t spend without noticing.

personal finance savings automation habits
Habits

Project your end-of-month balance (and act before it happens)

August 20, 2026

You open your banking app, see 1,400 in your account, and relax. The problem is that number only tells you how much you have today, not how much you’ll have on the 28th, once rent, the electricity bill, and the gym membership have all gone out. Looking only at today’s balance is like driving while staring at the rearview mirror: it tells you where you’ve been, not what’s ahead.

The tip: project, don’t just look

The idea is simple and doesn’t need any complicated tool: instead of asking “how much do I have?”, ask “how much will I have on the last day of the month?” To answer that, you only need two lists you already know by heart:

personal finance balance forecast budgeting habits
Habits

Latte-factor spending: the small leaks that drain your account

August 17, 2026

You go over the month and there’s no single big expense that explains it. No emergency, no unusual purchase. And yet the numbers still don’t add up the way you expected. Chances are the problem isn’t a big expense at all, but a leak of small ones: the coffee on the way to work, the app that renews itself, Thursday’s takeout order because you didn’t feel like cooking. Each one looks harmless on its own. Together, they’re the difference between saving something and saving nothing.

personal finance small spending savings habits